Local Insurance Agency serving Catalina Foothills
Catalina Foothills Wildfire Insurance
Helpful Resources for Homeowners Concerned About Wildfires in Catalina Foothills

Explore these valuable resources compiled by RIGHTSURE to understand the wildfire risks specific to Catalina Foothills and the Greater Tucson area, find tips on how to reduce your risk of damage to your home or business, and how to review the specific coverage included on (or excluded from) your home insurance policy.
Need help uncovering the specifics buried in your policy? Connect with one the Famously Friendly Humans at RIGHTSURE.
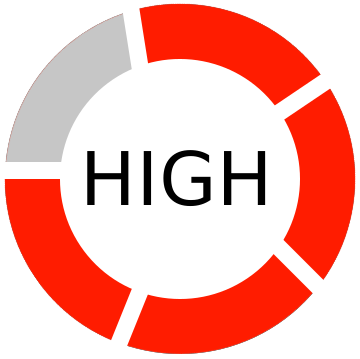
Homes in Catalina Foothills have on average greater risk than 73% of communities in the US.
Dig deeper into wildfire causes, risks, maps and data specific to Catalina Foothills, AZ with these resources from Wildfire Risk to Communities from the USDA Forest Service:
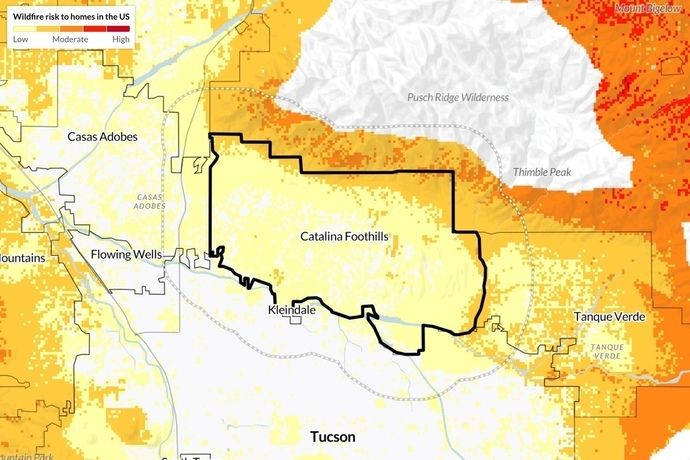
Source: Wildfire Risk in Catalina Foothills, AZ. USDA Forest Service, Wildfire Risk to Communities 2024
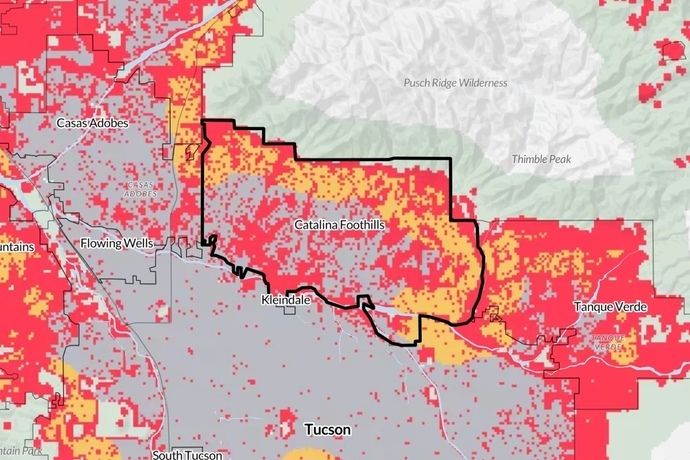
Wildfire Risk Reduction Zones in Catalina Foothills, AZ. Sources: USDA Forest Service, Wildfire Risk to Communities v2.2026
You can reduce the risk and severity of wildfire damage to your home and community by taking proactive steps now.
Learn more about how to choose wildfire-resistant materials, maintain landscaping and practice safe outdoor storage with these guides from wildfirerisk.org:
Risk Reduction Zones are the areas where mitigation activities will be most effective at protecting homes and other buildings from wildfires.
Homes are not likely to be subjected to wildfire.
Area near homes where flammable vegetation may expose homes to wildfire.
Homes may be ignited by indirect sources such as embers and home-to-home ignition.
Homes may be ignited by adjacent flammable vegetation, as well as indirect sources.
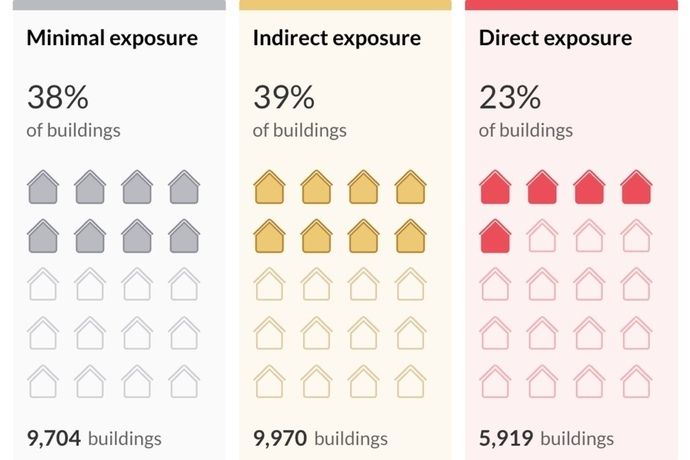
% of Buildings in Catalina Foothills, AZ in Each Wildfire Risk Reduction Zone. Sources: USDA Forest Service, Wildfire Risk to Communities v2.2026
Questions to Ask Your Agent or Carrier About Your Homeowner Insurance Policy & Wildfire Coverage
For an even deeper understanding of your coverage, review this full list of questions to consider about wildfire coverage for homes in Catalina Foothills.
Most-Read Wildfire Resources from RIGHTSURE: Award-Winning Insurance Agency in Tucson, AZ & Home of the Famously Friendly Humans
Homeowners insurance generally covers damage caused by wildfire, including covered damage to the home and personal belongings. However, coverage depends on the specific policy, its limits, conditions, and exclusions.
Read more about Brush Fire Property Defense
A friendly human at RIGHTSURE can review your entire policy with you to make sure you fully understand what coverage you currently have in place.
Not necessarily. Fire damage, including wildfire damage, is generally covered under standard homeowners insurance. Review your policy to confirm the coverage provided, especially if your home is in an area with wildfire exposure.
Read more about Wildfire Risk Scores.
Yes, wildfire risk scores may influence underwriting, renewals, premiums, and eligibility (depending on the carrier).
Read more about Wildfire Risk Scores.
Smoke and soot damage may be covered under homeowners insurance, even when the home has not been directly burned. Coverage depends on the cause of damage and the policy's terms, conditions, and exclusions.
Additional living expense coverage may pay for reasonable extra living costs when a covered event displaces you from your home. Some policies also provide limited coverage for evacuation ordered by authorities. Check your policy for eligibility, time limits, and coverage amounts.
Some homeowners insurance policies provide limited coverage for trees and shrubs damaged by fire. Coverage amounts and eligible property vary, so review your policy's landscaping limits and exclusions.
A useful starting point is your home's estimated replacement cost, rather than its market value. Review your dwelling coverage limit, personal property coverage, and additional living expense limits to understand how your policy would respond to a major covered fire loss.
Standard homeowners insurance generally does not cover flood damage, even when flooding occurs after a wildfire. Flood insurance is separate. Burned landscapes can increase runoff and flooding risk, making this an important distinction for homeowners to understand.
RIGHTSURE is an award-winning independent insurance agency providing reliable, honest, friendly & dependable insurance services to the families and businesses in Tucson, Sierra Vista, Pima County, Catalina Foothills, Sahuarita, Oro Valley, Marana, Catalina, Green Valley, Rio Rico, Willcox, Benson, Casas Adobes, and Tombstone, as well as across the entire state of Arizona and 33 other states.
I had a wonderful and easy experience, Marissa helped me and she’s amazing!
Great company, easy to work with and very friendly!
They did an awesome job with my insurance policy brought the cost way down. Very happy with this outfit.
Marissa was very helpful and sooo kind. She answered all my questions and helped me understand my insurance coverage.
Great to work with. Made the process so simple and easy. Definitely recommend
Jennifer was super amiable and made the process a breeze! Saved me a chunk of cash too